Allstate Homeowners Insurance Quote: Coverage, Costs, Discounts and What to Know.
Introduction
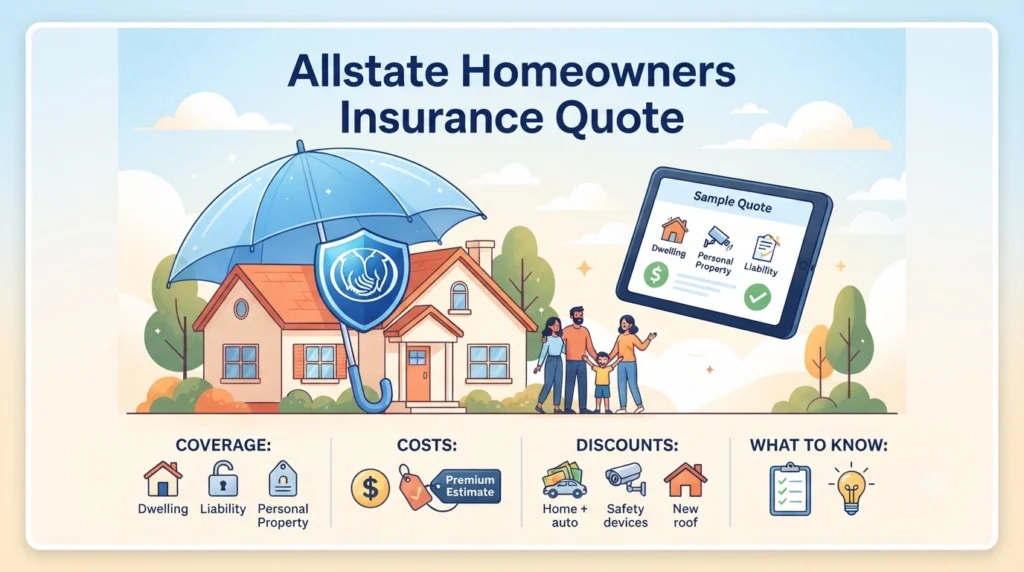
An Allstate homeowners insurance quote gives you an estimate of what you may pay for coverage designed to protect your home, belongings and financial interests against covered losses. The final premium is not a universal price because Allstate considers information about the property, its condition, location, requested coverage, limits and deductibles when preparing a quote.
For homeowners, the most useful way to evaluate a quote is not simply to look for the lowest premium. You also need to understand what the policy covers, how much protection you are getting, what exclusions apply, how the deductible works and whether discounts or optional coverages could change the overall cost.
This guide explains how the Allstate homeowners insurance quote process works, what information you may need, the major coverage types, ways to potentially reduce the premium and what to check before purchasing a policy.
Quick Answer: What Is an Allstate Homeowners Insurance Quote?
An Allstate homeowners insurance quote is an estimate of the premium and coverage options available for a particular home and policy configuration.
Allstate states that homeowners quotes can require personal and property information, including details about the home’s condition, renovations and amenities. The coverage amounts, limits and deductibles selected also influence the cost.
A quote may therefore change when you modify factors such as:
- Dwelling coverage
- Personal property limits
- Liability limits
- Deductibles
- Optional coverage
- Property characteristics
- Location
- Home improvements
- Available discounts
The exact availability and policy features can also vary by state. Allstate maintains state-specific home insurance information because homeowners coverage is not identical throughout the country.
What Does Allstate Homeowners Insurance Cover?
A standard homeowners policy can contain several different types of protection. The precise terms, exclusions, limits and availability depend on the policy and location.
Allstate identifies several common homeowners coverage categories, including dwelling, personal property, other structures, liability, guest medical protection and additional living expenses.
1. Dwelling Coverage
Dwelling coverage is designed to help pay for repairing or rebuilding the physical structure of your home after a covered loss.
It can include major components such as:
- Walls
- Roof
- Attached structures
- Other parts of the home’s physical structure
The amount of dwelling coverage is important because it should be based on the estimated cost to rebuild rather than simply the home’s real-estate market value.
Allstate’s home insurance resources explain that dwelling coverage may help pay to repair or rebuild the home after a covered loss.
2. Personal Property Coverage
Your house is only one part of what needs protection.
Furniture, electronics, clothing and other belongings can also represent substantial value. Personal property coverage may help repair or replace belongings after a covered event, subject to policy limits and terms.
Allstate explains two important approaches to personal-property protection:
Actual cash value: The value considers depreciation.
Replacement cost: The coverage can pay the cost of purchasing a new item of the same kind and quality, subject to the policy terms.
Homeowners should therefore check which valuation method applies to their policy.
3. Other Structures Coverage
Detached structures on your property may need separate protection.
Examples can include:
- Detached garages
- Sheds
- Fences
- Other qualifying structures
The amount and scope of this coverage depend on the policy.
4. Personal Liability Protection
Liability coverage can help protect you financially if you are legally responsible for another person’s injury or property damage.
For example, someone could be injured at your home and pursue compensation. Personal liability protection may help with covered legal defense costs, settlements and other eligible expenses, subject to policy limits and exclusions.
Liability coverage can also be relevant to certain incidents away from your property.
5. Guest Medical Protection
Some homeowners policies include protection that can help with qualifying medical expenses when a guest is injured on your property.
This coverage is different from personal liability coverage and operates according to its own policy terms and limits.
6. Additional Living Expenses
If a covered loss makes your home temporarily uninhabitable, additional living expenses coverage may help with certain increased costs associated with living elsewhere while repairs are made.
The exact expenses covered and applicable limits depend on the policy.
What Information Do You Need for an Allstate Homeowners Insurance Quote?
Getting a useful quote requires accurate information about both you and the property.
Allstate says homeowners insurance quotes may require information about the home, including renovations, condition and amenities. The coverage limits and options requested also affect the quote.
Before starting, you may want to have information such as:
Property details
You may be asked about:
- Property address
- Type of home
- Construction details
- Approximate age
- Roof information
- Number of rooms
- Home features
- Detached structures
Home improvements
Recent upgrades can be relevant to insurance underwriting.
Examples include:
- Roof replacement
- Plumbing updates
- Electrical improvements
- Heating-system changes
- Security upgrades
- Renovations
Keeping these details accurate can help produce a more appropriate quote.
Current insurance information
If you already have homeowners insurance, information from your current policy can make comparison easier.
Review:
- Current premium
- Dwelling limit
- Personal-property limit
- Liability limit
- Deductibles
- Discounts
- Policy expiration date
Your declarations page is particularly useful because it summarizes the coverage, limits, deductibles and premium associated with your policy.
How Much Does Allstate Homeowners Insurance Cost?
There is no single Allstate homeowners insurance price that applies to every property.
Two houses in different locations can have very different premiums even if they have similar sizes. Likewise, two homes next door to each other can receive different quotes because of differences in construction, coverage selections, claims history, deductibles or other rating factors.
Allstate’s quote process uses property and personal information to determine the applicable pricing and coverage.
Factors that can influence the cost may include:
- Location
- Home characteristics
- Construction
- Roof condition
- Coverage limits
- Deductible
- Claims history
- Protective devices
- Bundling
- Available discounts
- Optional coverage
Because of these variables, online articles showing a single “average Allstate homeowners insurance quote” should not be treated as a personalized price.
The most useful comparison is between quotes with similar coverage limits and deductibles.
How Can You Get an Allstate Homeowners Insurance Quote?
Allstate provides an online quote option through its home insurance website. You can also work with an Allstate agent.
A typical process looks like this:
Step 1: Start the quote
Begin through Allstate’s home insurance quote process.
Step 2: Enter property information
Provide the requested information about your home and property.
Step 3: Select coverage
Your quote depends partly on the coverage and limits you choose.
Step 4: Review deductible options
A deductible is the amount you generally pay toward a covered claim before the applicable insurance coverage responds.
Allstate explains that choosing a higher deductible usually means a lower premium, although it also means taking on more out-of-pocket expense if you have a covered claim.
Step 5: Check available discounts
Review which discounts you may qualify for.
Step 6: Compare the policy details
Don’t stop at the premium.
Compare:
- Coverage limits
- Deductibles
- Exclusions
- Optional coverage
- Personal-property valuation
- Liability protection
- Available discounts
Step 7: Review the final policy
Before purchasing, verify that the information about your property and selected coverage is accurate.
Allstate Homeowners Insurance Discounts
Discounts can make a meaningful difference in the final premium, but eligibility varies.
Allstate currently lists several homeowners savings opportunities.
Multi-Policy Discount
Bundling home and auto insurance with Allstate may provide a multi-policy discount.
Allstate currently advertises home-and-auto bundle savings and says customers can receive an average 20% savings when bundling auto and home policies, subject to the applicable terms and qualifications.
Claim-Free Discount
Customers without a recent home insurance claim may qualify for claim-free savings.
Responsible Payer Discount
Allstate lists savings opportunities related to payment history and payment methods.
Protective Device Discount
Qualifying safety and security equipment may help reduce premiums.
Examples can include:
- Burglar alarms
- Smoke detectors
- Fire extinguishers
- Sprinkler systems
- Monitored fire alarms
- Deadbolts
Eligibility depends on the insurer’s requirements.
Home Buyer Discount
Allstate lists a discount opportunity for qualifying recent homebuyers and newly constructed homes.
Automatic Payment Savings
Eligible customers may also receive savings through qualifying automatic-payment arrangements.
Early Signing Discount
Allstate lists an early-signing discount for customers who sign up for a new policy at least seven days before their current policy expires, subject to eligibility.
Does Bundling Home and Auto Insurance Save Money?
Bundling can reduce insurance costs for some customers.
Allstate currently promotes home-and-auto bundling as a way to receive a multi-policy discount and says customers can save an average of 20% when bundling home and auto insurance, subject to the applicable conditions.
However, homeowners should compare the combined cost and coverage, rather than assuming that bundling automatically produces the lowest overall price.
For example, another insurer could potentially offer a lower standalone home policy or auto policy even if Allstate provides a bundle discount.
A useful comparison looks at:
- Home premium
- Auto premium
- Combined premium
- Coverage limits
- Deductibles
- Discounts
- Optional protections
How Do Deductibles Affect an Allstate Quote?
The deductible is one of the most important pricing choices in a homeowners policy.
Suppose two otherwise similar policies offer different deductibles. The policy with the higher deductible may have a lower premium, but you would generally have to pay more yourself after a covered loss.
Allstate explains that deductibles apply to certain coverage types and are shown in the policy declarations. It also notes that a higher deductible usually results in a lower premium.
The key is to select a deductible that you could realistically afford if you needed to file a claim.
A lower monthly premium is not necessarily helpful if the deductible would create financial difficulty after a major loss.
What Is Not Automatically Covered?
Homeowners insurance does not mean every possible type of property damage is automatically covered.
Coverage depends on the policy’s covered causes of loss, exclusions, limits and endorsements.
For example, Allstate’s personal-property information notes that lost items and flood damage are typically not covered by standard personal-property protection without additional coverage.
Flood risk deserves particular attention because standard homeowners insurance generally should not be treated as a substitute for dedicated flood insurance.
Other situations can also require separate or additional protection.
Depending on the property and circumstances, homeowners may want to investigate:
- Flood insurance
- Scheduled personal property
- Personal umbrella insurance
- Special coverage for high-value belongings
- Other optional endorsements
Always review the actual policy language before assuming a specific loss is covered.
What Is Scheduled Personal Property?
Standard personal-property coverage may contain limits for certain high-value categories.
If you own expensive jewelry, collectibles or other valuable possessions, scheduled personal property coverage may provide additional protection.
Allstate specifically identifies scheduled personal property as an optional way to protect high-value belongings such as jewelry when standard policy limits may not provide enough protection.
Homeowners should keep receipts, appraisals and other documentation where appropriate.
How to Compare an Allstate Quote With Other Insurers
Comparing insurance quotes only by price can produce a misleading result.
Instead, request comparable coverage from multiple insurers.
For each quote, record:
| Comparison Point | What to Check |
|---|---|
| Dwelling coverage | Is the rebuilding limit adequate? |
| Personal property | Is the limit appropriate for your belongings? |
| Liability | How much protection is provided? |
| Deductible | What would you pay after a covered claim? |
| Additional living expenses | What protection is included? |
| Other structures | Are detached structures adequately covered? |
| Optional coverage | What endorsements are included? |
| Discounts | Which discounts apply? |
| Premium | What is the total policy cost? |
| Exclusions | What important risks are not covered? |
Allstate itself recommends shopping around and comparing similar coverage amounts when evaluating home insurance costs.
Is an Allstate Homeowners Insurance Quote the Final Price?
Not necessarily.
A quote is an estimate based on the information provided and the policy options selected during the quoting process.
The final premium can depend on verification, underwriting, selected coverages, property characteristics, discounts and applicable state rules.
This is why homeowners should provide accurate information rather than deliberately entering incomplete or incorrect details simply to obtain a lower initial estimate.
The goal should be a quote that accurately reflects the home and the protection you actually need.
Tips for Getting a More Useful Home Insurance Quote
1. Know the home’s rebuilding cost
The amount required to rebuild a home can differ from its market value.
Allstate’s coverage calculator describes rebuilding cost as the amount needed to rebuild the house using current construction materials, labor and related costs.
2. Inventory your belongings
Create a home inventory containing major possessions and useful documentation.
Photos, receipts and records can make it easier to understand how much personal-property coverage you may need.
3. Review your deductible
Don’t choose a deductible solely because it produces a lower premium.
Consider how much you could afford after a covered loss.
4. Ask about every available discount
Allstate lists multiple potential discounts, but eligibility varies.
Ask which discounts apply to your property rather than assuming every advertised discount will be available.
5. Compare equivalent policies
When comparing insurers, keep the coverage limits and deductibles as similar as possible.
6. Review the declarations page
Your declarations page shows important information such as the premium, coverage, limits and deductibles.
7. Recheck your policy after major changes
Home renovations, new valuables, changes in household circumstances or other property changes can affect insurance needs.
Frequently Asked Questions
How do I get an Allstate homeowners insurance quote?
You can start through Allstate’s online home insurance quote process or contact an Allstate representative. You’ll generally need information about your property and the coverage you want.
How much does Allstate homeowners insurance cost?
There is no single price for every homeowner. Premiums depend on factors such as location, property characteristics, coverage limits, deductibles, claims history and discounts.
Does Allstate offer home insurance discounts?
Yes. Allstate lists several potential discounts, including multi-policy, claim-free, responsible-payer, protective-device, homebuyer and other savings opportunities. Eligibility varies.
Can I bundle Allstate home and auto insurance?
Yes. Allstate offers home-and-auto bundling and currently advertises average savings of 20% for customers who bundle, subject to applicable conditions.
Does homeowners insurance cover personal belongings?
Personal-property coverage can help repair or replace eligible belongings after covered losses, subject to limits and policy terms. Allstate offers actual-cash-value and replacement-cost approaches for personal property depending on the policy.
Does Allstate homeowners insurance cover floods?
Standard homeowners insurance should not be assumed to cover flood damage. Additional flood coverage may be necessary depending on the property and circumstances.
Does a higher deductible lower homeowners insurance costs?
Generally, a higher deductible can result in a lower premium. However, it also means greater out-of-pocket responsibility after a covered claim.
What should I compare when reviewing an Allstate quote?
Compare the premium alongside dwelling coverage, personal-property limits, liability protection, deductibles, exclusions, additional coverage and discounts. A lower price is not necessarily comparable if the coverage is different.
Final Thoughts
An Allstate homeowners insurance quote is more than a number on a screen. It represents a combination of coverage limits, deductibles, property characteristics, available discounts and policy options.
Allstate offers homeowners coverage for areas such as the dwelling, personal property, liability, other structures and additional living expenses, while optional protections can address specific needs.
The right way to evaluate a quote is to look beyond the premium. Check whether the dwelling limit is appropriate, whether your belongings are adequately protected, whether the liability limit fits your situation, whether the deductible is affordable and whether you qualify for available discounts.
Because homeowners insurance varies by state and individual property, obtaining a personalized quote and comparing equivalent coverage from multiple insurers can give you a more meaningful picture of your options.